Why Is It So Difficult for India’s Middle Class to Save Money?
India’s
Why Is It Becoming So Difficult for India’s Middle Class to Save Money?
Introduction
For millions of Indian families, earning money is only half the challenge. The bigger challenge is saving enough to build a secure future.
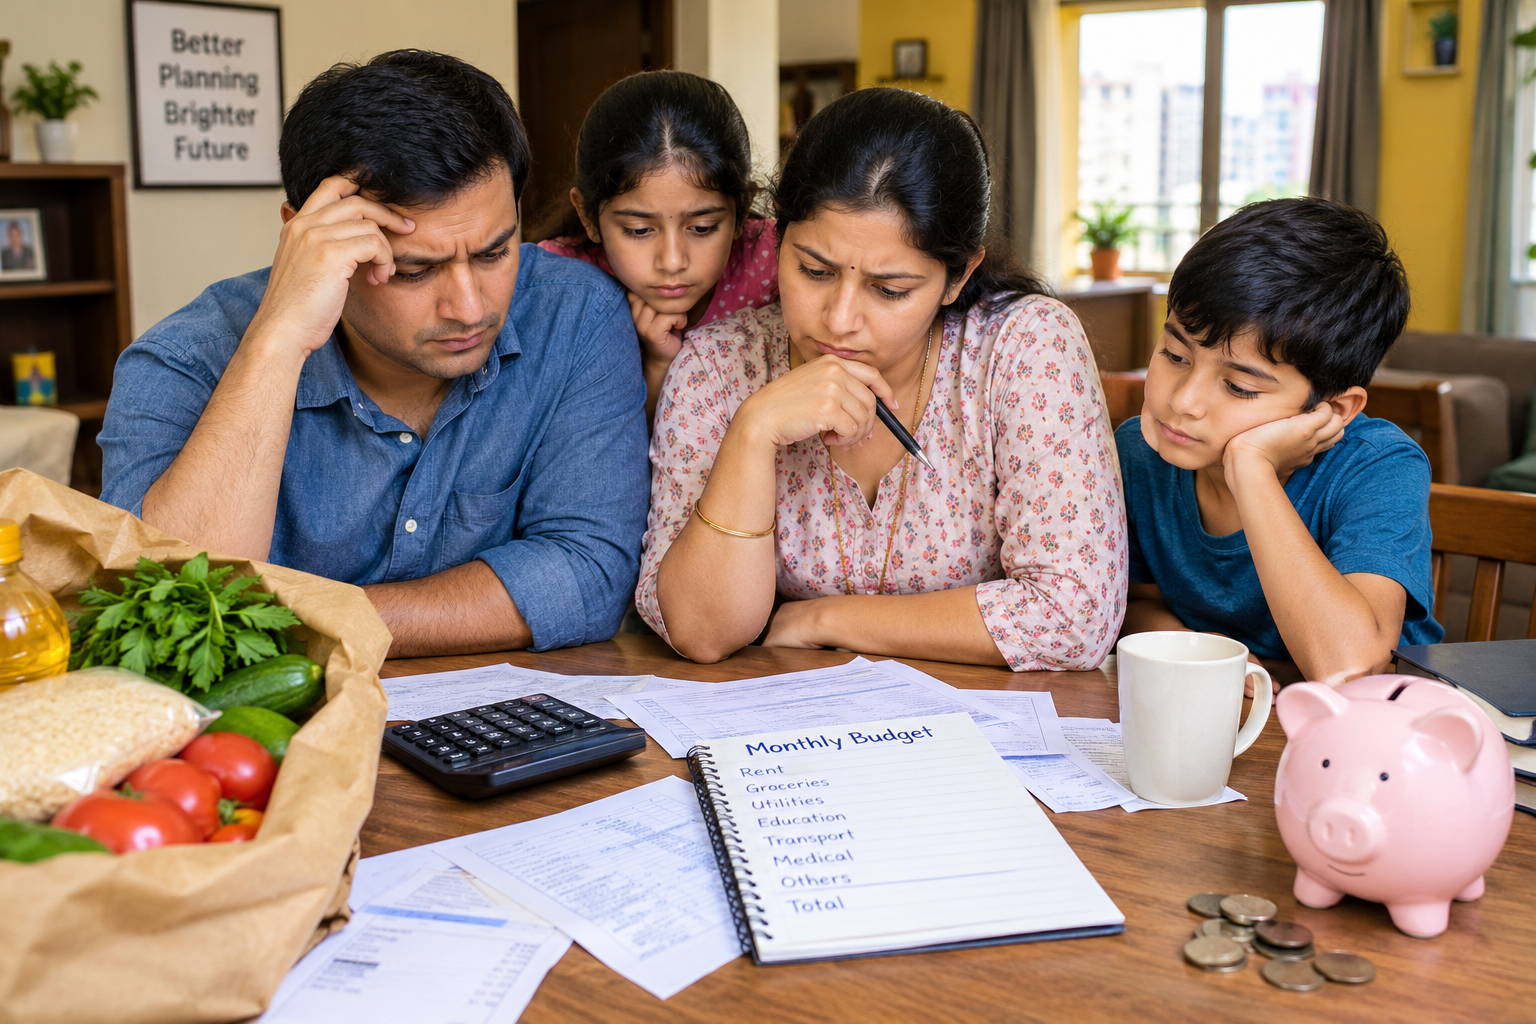
A person may have a regular job, receive a monthly salary, and manage household expenses carefully, yet still struggle to save money at the end of the month. Rent, groceries, electricity bills, school fees, transportation, medical expenses, and loan payments can consume a large portion of household income.
The situation becomes even more complicated when people want to buy a home, support their parents, provide quality education to their children, and prepare for retirement.
This raises an important question: Why is it becoming so difficult for India’s middle class to save money, even when people are working hard and earning a regular income?
The answer is not simply poor financial planning. Rising living costs, changing lifestyles, expensive housing, family responsibilities, debt, and uncertainty about the future can all influence a family’s ability to save.
Understanding these challenges is the first step toward building a healthier financial future.
1. Rising Household Expenses Are Eating Into Salaries
One of the biggest challenges for middle-class families is the growing pressure of everyday expenses.
Food, cooking gas, electricity, transportation, household supplies, and other essentials are recurring costs. Families cannot simply stop buying groceries or paying their electricity bills when prices increase.
Even small price increases can make a difference over an entire month.
Imagine a family that spends ₹12,000 on groceries and essential household items each month. If its expenses increase, even modestly, the family may need to spend several hundred or more additional rupees without receiving a corresponding salary increase.
The pressure becomes greater when several expenses rise at the same time.
Recent Indian inflation data has also shown that prices can fluctuate significantly. For example, retail inflation reached 5.54% year-on-year in September 2026, with food prices contributing to the increase. This is a national measure, not the personal inflation rate of every household, but it illustrates why essential expenses deserve attention.
When a larger share of income goes toward necessities, less money remains for savings, investments, and emergencies.
2. Salary Growth Does Not Always Feel Like Financial Progress
Getting a salary increase should make life easier. However, a higher salary does not automatically mean a person can save more money.
Suppose someone receives a monthly salary of ₹30,000 and later gets a raise to ₹35,000. The additional ₹5,000 may seem like a meaningful improvement.
But what happens if rent increases, groceries become more expensive, transportation costs rise, and the person takes on new responsibilities?
The additional income may disappear before it can be saved.
This happens because financial progress depends on the relationship between income and expenses, not just the salary figure.
If expenses grow at the same pace as income, a person may continue to feel financially stuck despite earning more than before.
The practical lesson is simple: whenever income increases, consider directing a portion of the raise toward savings before increasing discretionary spending.
3. Housing Has Become a Major Financial Responsibility
For many middle-class Indians, finding affordable housing is one of the biggest financial challenges.
In major cities, monthly rent can consume a substantial share of a household’s take-home income. In addition to rent, families may need to pay maintenance charges, electricity bills, deposits, commuting costs, and other housing-related expenses.
Buying a home can create a different set of financial pressures.
A home loan may provide long-term stability and help a family own an asset, but monthly instalments can reduce the amount available for other goals. Buyers must also consider registration charges, maintenance, repairs, insurance, and furnishing costs.
For example, a family paying ₹20,000 in monthly rent may find it difficult to save for a down payment while also meeting daily expenses.
Another family paying a large home-loan instalment may have little flexibility when unexpected costs arise.
Housing is not necessarily a bad financial decision. The problem occurs when housing costs become so large that a family cannot maintain an emergency fund or save for other important goals.
4. Education and Children’s Future Require Long-Term Planning
Parents want to provide their children with good educational opportunities. However, education can involve much more than school fees.
Families may need to pay for books, uniforms, transportation, coaching classes, extracurricular activities, technology, examination fees, and higher education.
These expenses can become particularly challenging when a household has more than one child.
Parents may also feel pressure to spend more because they believe better opportunities require expensive schools, additional classes, or costly preparation programmes.
Some of these expenses may be valuable, but others deserve careful evaluation.
The challenge is that education costs often increase over several years, while parents must continue paying for food, housing, healthcare, and other essentials.
Planning early can help. Families can estimate future education costs, contribute regularly to a dedicated savings fund, and compare educational options based on quality and affordability rather than price alone.
The aim should be to support a child’s future without putting the entire family’s financial security at risk.
5. Lifestyle Inflation Makes Saving More Difficult
As income grows, spending habits often change.
Someone who previously used public transportation may begin using taxis more frequently. A person who once ate at home most days may start ordering food regularly. Families may upgrade their smartphones, purchase new appliances, or spend more on entertainment.
There is nothing inherently wrong with enjoying the money earned through hard work.
The difficulty begins when every increase in income is followed by a similar increase in spending.
This is known as lifestyle inflation.
For example, imagine a person who earns ₹40,000 per month and manages to save ₹5,000. After receiving a raise, the person begins spending more on dining out, shopping, subscriptions, and weekend activities. Despite earning more, the monthly savings may remain unchanged.
Over time, lifestyle inflation can prevent people from building an emergency fund or accumulating money for major goals.
One helpful approach is to separate essential expenses, planned enjoyment, and future savings. This allows people to enjoy their income while ensuring that financial goals continue to receive attention.
6. Easy Credit Can Create Long-Term Financial Pressure
Credit cards, personal loans, consumer financing, and buy-now-pay-later services can make purchases easier.
They can also make it harder to recognise how much money has already been committed to future payments.
A person may purchase a phone through monthly instalments, use a credit card for shopping, and take another loan to manage an unexpected expense. Each individual payment may appear manageable, but several payments together can create a serious burden.
Credit card interest can be particularly expensive when the full outstanding balance is not paid by the due date.
Loan payments also reduce monthly flexibility. Money used to repay debt is no longer available for groceries, savings, investments, or emergencies.
This does not mean every loan is harmful. Borrowing for carefully planned goals can be reasonable. The important factors are affordability, repayment terms, interest costs, and the borrower’s ability to manage unexpected changes in income.
Before taking on new debt, families should calculate the total monthly repayments and consider whether they can still save and meet essential expenses.
7. Family Responsibilities Can Reduce Personal Savings
In India, financial decisions are often connected to the needs of the entire family.
An adult may contribute toward household expenses, support elderly parents, pay for a sibling’s education, or help relatives during emergencies.
These responsibilities can be meaningful and important. However, they can also make personal financial planning more complicated.
A person may intend to save ₹8,000 every month but end up using that money for medical expenses, family functions, household repairs, or another urgent need.
When these responsibilities are unpredictable, saving becomes difficult even for people who manage their regular budgets carefully.
One solution is to distinguish between routine family support and unexpected family expenses. If possible, both should have separate budget allocations.
Families can also discuss financial priorities openly so that one person does not have to carry every responsibility without a plan.
Saving for oneself is not selfish. Maintaining financial stability can make it easier to help family members when they genuinely need support.
8. Medical Emergencies Can Wipe Out Years of Savings
Health-related expenses can disrupt even a carefully prepared household budget.
A sudden illness, accident, hospital admission, or long period without work can create costs that were never included in regular monthly spending.
Even when a family has health insurance, certain expenses may remain, depending on policy terms, exclusions, deductibles, limits, and treatment requirements.
Without adequate protection or emergency savings, households may have to borrow money or withdraw funds intended for education, retirement, or a home purchase.
This is why an emergency fund is so important.
A practical starting goal is to save enough to cover one month of essential expenses, then gradually work toward a larger reserve. The appropriate amount depends on job stability, dependants, health needs, and other circumstances.
Families should also review their insurance coverage and understand what their policies actually cover.
Preparation cannot eliminate every financial shock, but it can reduce the damage an emergency causes.
9. Social Media Creates Pressure to Spend More
Today’s consumers are constantly exposed to images of expensive holidays, fashionable clothing, new gadgets, luxury homes, and seemingly perfect lifestyles.
Social media can make it appear that everyone else is earning more, travelling more, and enjoying a better life.
This can encourage people to spend money to maintain appearances or avoid feeling left behind.
For example, someone may purchase an expensive phone because friends have upgraded theirs, even though the current phone works perfectly well.
Another person may take on debt to pay for a holiday or celebration that is beyond their budget.
The problem is not social media itself. The problem is comparing personal financial circumstances with carefully selected images of other people’s lives.
A healthier approach is to define success according to personal priorities. For one person, success may mean owning a home. For another, it may mean being debt-free, supporting parents, or having enough savings to change careers.
Financial goals should reflect real needs rather than pressure to impress others.
10. Many People Have Never Been Taught How to Manage Money
People often spend years studying academic subjects and developing professional skills without receiving practical education about personal finance.
They may not know how to prepare a realistic budget, compare loan interest rates, calculate the effect of inflation, understand insurance policies, or evaluate investment risks.
As a result, some people save whatever money remains at the end of the month rather than setting aside savings first.
Others may leave all their money in a regular account without considering their goals, while some may invest in products they do not fully understand.
Financial knowledge does not guarantee wealth, and limited savings are not always caused by poor decisions. When income barely covers essential expenses, even excellent budgeting cannot create money that is not available.
However, learning basic financial skills can help people make better use of the income they do have.
Understanding spending patterns, debt costs, savings options, and risk can make financial decisions more informed and less stressful.
11. How India’s Middle Class Can Start Saving More Money
Although the challenges are real, small and consistent changes can improve financial stability over time.
Create a realistic monthly budget
Record monthly take-home income and list essential expenses such as housing, food, transport, education, utilities, and debt repayments.
Then identify discretionary spending that can be reduced without harming essential needs.
A budget should reflect actual life, not an unrealistic ideal.
Save before spending
If your income allows it, transfer a manageable amount into a separate savings account soon after receiving your salary.
Start with an amount you can sustain. Even ₹500 or ₹1,000 a month can help establish a savings habit, although larger goals require larger contributions.
If your essential expenses already exceed your income, focus first on addressing that shortfall.
Build an emergency fund
Start small and increase the fund gradually.
Keep emergency money accessible and separate from money intended for long-term goals. Avoid placing all emergency savings in investments that may fluctuate significantly in value or be difficult to withdraw quickly.
Review subscriptions and recurring payments
Check mobile plans, streaming services, memberships, delivery fees, and automatic payments.
Cancel services you rarely use and compare alternatives where practical. Small savings can add up over time.
Manage debt carefully
Prioritise expensive debt, understand the terms of every loan, and avoid taking new credit simply to maintain a lifestyle.
If repayments have become difficult, contact the lender early to understand legitimate options rather than ignoring the problem.
Plan for major expenses
Education, annual insurance premiums, home repairs, festivals, and family events are often predictable even if they do not occur every month.
Estimate these costs and set aside money gradually to reduce the need for borrowing.
Increase earning opportunities where possible
Budgeting has limits. When essential expenses consume nearly all available income, improving earning capacity may be more effective than cutting every small pleasure.
Depending on a person’s circumstances, options may include developing professional skills, pursuing better-paid work, negotiating compensation, or building a carefully planned additional income stream.
Any new opportunity should be assessed for its costs, risks, and time requirements.
Set realistic financial goals
Instead of focusing only on becoming wealthy, establish achievable milestones: paying off expensive debt, building an emergency fund, saving for education, or contributing regularly toward retirement.
Progress becomes easier to measure when goals are specific and realistic.
12. Why Saving Money Is About More Than Discipline
It is easy to tell people to stop spending and save more. In reality, financial security depends on several factors working together.
Income must be sufficient to cover basic needs. Essential expenses must remain manageable relative to earnings. Families need access to appropriate financial products, and unexpected costs must not repeatedly destroy their progress.
A person earning a low salary in an expensive city may have far fewer opportunities to save than someone with a higher income and fewer responsibilities.
Similarly, a family dealing with medical expenses or supporting several dependants may face constraints that cannot be solved simply by cancelling subscriptions.
Recognising these differences is important.
Good financial habits can help people make progress, but financial security also depends on employment opportunities, affordable services, health protection, and the wider economic environment.
The goal should not be to blame people for struggling. It should be to understand their circumstances and identify practical ways to improve them.
Conclusion
Saving money has become a complicated challenge for many Indian middle-class families because multiple responsibilities compete for the same monthly income.
Rising household expenses, housing costs, education, family commitments, medical emergencies, lifestyle inflation, and debt can leave little room for financial growth.
The solution is not necessarily to stop enjoying life or avoid every purchase. It is to understand where money goes, prioritise important goals, prepare for emergencies, and make financial decisions based on personal circumstances.
For some households, saving more may begin with reducing unnecessary expenses. For others, the most important step may be managing debt, improving income, or getting better protection against unexpected costs.
Every family’s situation is different, but one principle remains useful: financial progress begins with a clear understanding of the money coming in, the money going out, and the goals that matter most.
The real aim is not simply to save more money every month. It is to build a life in which one unexpected expense does not destroy years of hard work.
Leave a Reply